Introduction
Systematic Dispute Deflection prevents friendly fraud by proving historic cardholder purchase activity with qualifying data. When a deflection is successful, the dispute is blocked by the card networks before it's raised. You retain the funds, prevent fraud claims (TC40s) from being filed, and reduce your dispute rate.
How it works
Section titled “How it works”-
Cardholder attempts a dispute
Section titled “Cardholder attempts a dispute”A cardholder contacts their bank to dispute a transaction.
-
Real-time lookup
Section titled “Real-time lookup”The card network performs a real-time lookup against your historical transaction data.
-
Dispute blocked
Section titled “Dispute blocked”If the criteria for deflection are met, the dispute is instantly blocked and never reaches you.
Historic purchase history
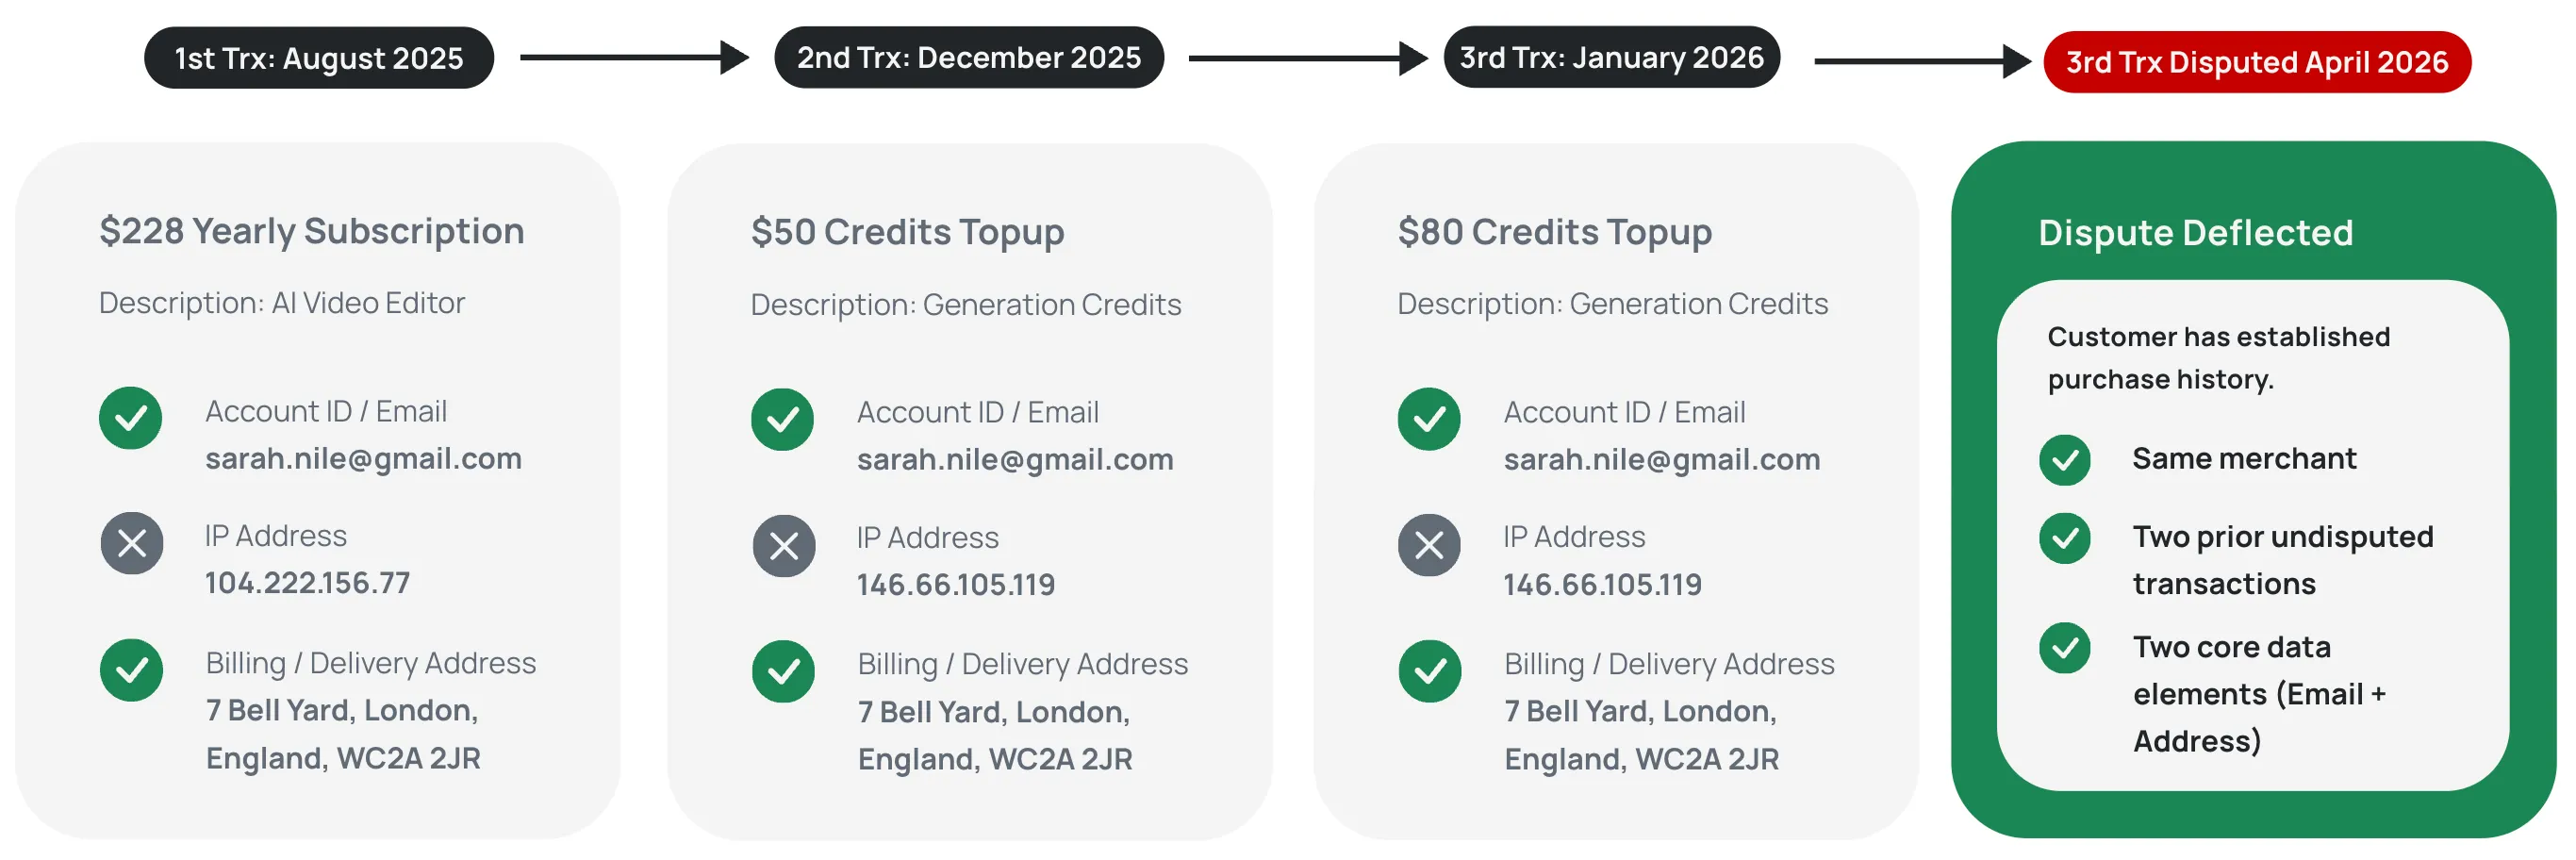
Section titled “Historic purchase history”A dispute becomes eligible for deflection when the cardholder has completed at least two previous transactions within 120 to 365 days before the disputed charge. These earlier transactions form the purchase history used to verify legitimacy.
Qualifying data
Section titled “Qualifying data”For a deflection to succeed, identifiers unique to the cardholder must match across the disputed transaction and the historic purchase history. Qualifying identifiers include:
- IP address
- Email address
- Device fingerprint
- Billing address
At least two identifiers must match, and one of them must be either an IP address or an email address.
Eligible dispute conditions
Section titled “Eligible dispute conditions”Currently, deflection is attempted for the following dispute conditions:
- Visa 10.4 — Card Not Present
- Mastercard 4814 — Card Not Present
Other conditions may become eligible as the card networks expand their programs.
Card network integration
Section titled “Card network integration”Systematic Dispute Deflection is powered by two card network solutions. We harmonise both systems into a single unified interface built to scale and support both programs as they evolve. You never need to integrate directly or manage those connections.
- Compelling Evidence 3.0 (Visa)
- First Party Trust (Mastercard)